Blog

  • Is Pet Insurance Worth It? The Honest Math (2026)

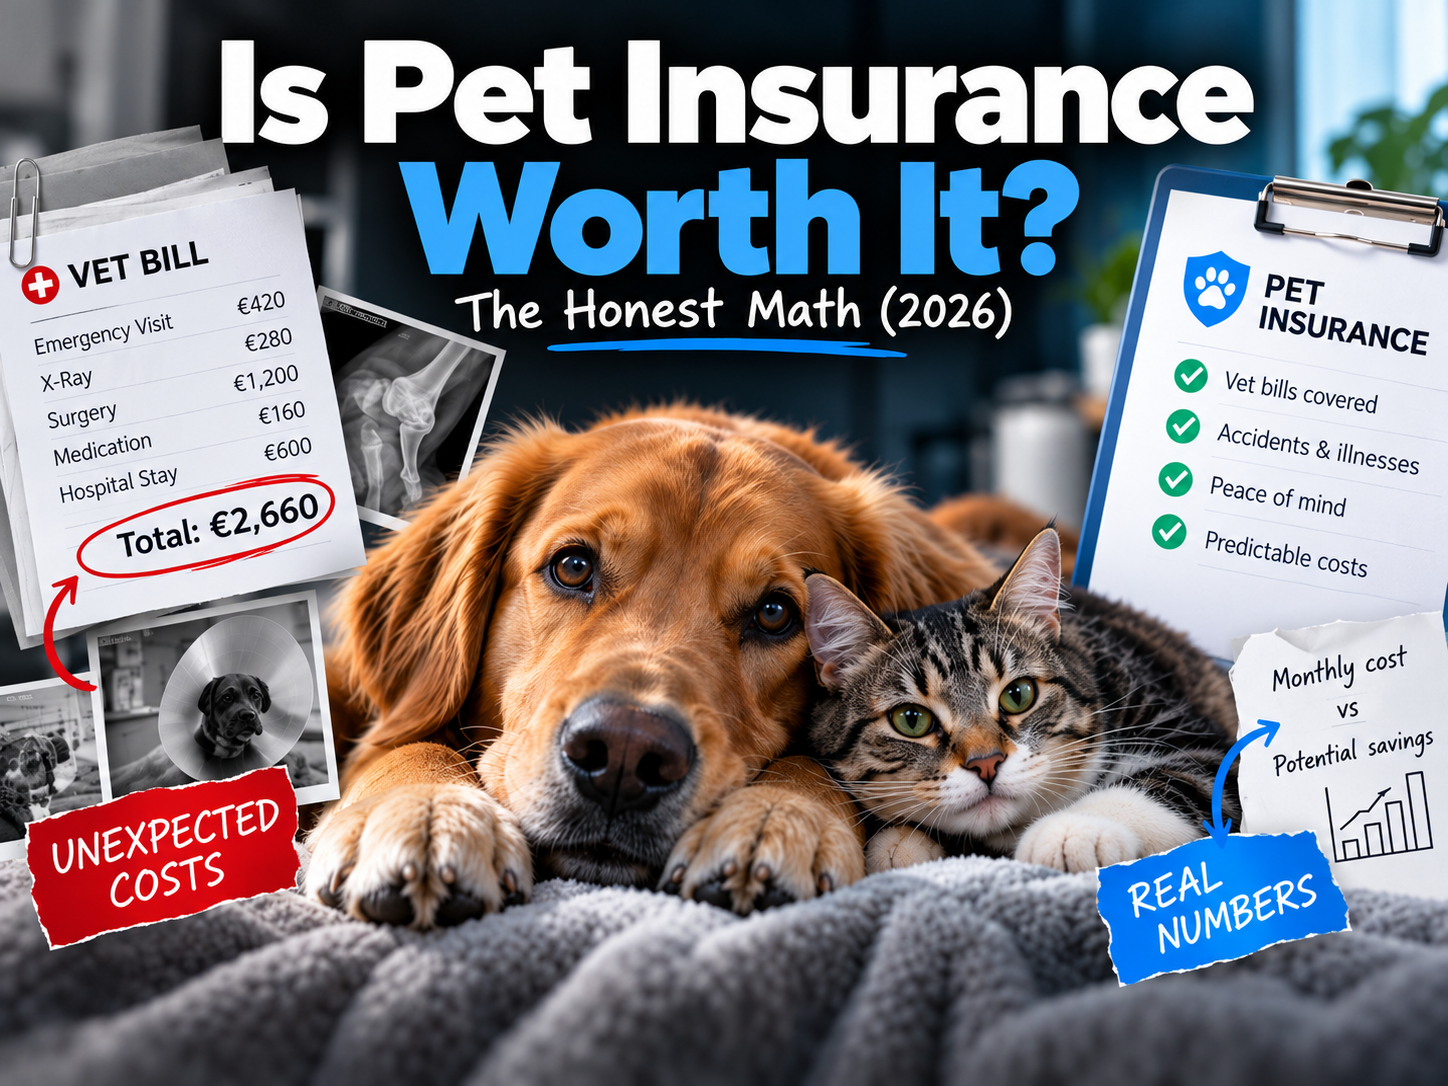
    Is Pet Insurance Worth It? The Honest Math (2026)

    Last updated: October 2026

    If your dog swallows a sock or your cat develops diabetes, the vet bill can run from a few hundred dollars to more than $10,000. Pet insurance is supposed to soften that blow — but the premiums add up too, and most pets never file a claim big enough to «pay back» what their owner spent on coverage. So is it actually worth it? The honest answer: it depends on the math, not on how much you love your pet.

    This guide walks through the real numbers — average premiums, average vet bills, and the breakeven point where insurance starts to win — so you can decide for your own pet instead of guessing.

    The short version: Pet insurance usually pays off if your pet has one serious accident or illness every few years, or develops a chronic condition. It usually doesn’t pay off if your pet stays healthy and you’d have actually saved the premium money instead. See [enlace: #1] for how the coverage itself works.

    The real math: premiums vs. vet bills

    Start with what each side of the bet actually costs. [enlace: #3]

    Average annual cost
    Accident & illness premium, dog$749–$836/year (~$62–$70/month)
    Accident & illness premium, cat$386–$435/year (~$32–$36/month)
    Ear infection$120–$300
    Basic ER visit$800+
    Overnight hospitalization$600–$6,500
    Parvo treatment (puppies)$1,000–$8,000
    Typical serious emergency$1,000–$10,000

    Premium ranges from NAPHIA’s 2025 State of the Industry report and Pawlicy; vet bill ranges from Pawlicy’s cost breakdown of US averages.

    Breakeven: how many vet visits make insurance pay off

    Take a dog on a typical plan: ~$800/year premium, 90% reimbursement, $250 deductible. [enlace: #4] [enlace: #5]

    • Zero vet emergencies in a year: you’re out the full $800 premium — insurance «loses.»
    • One $3,000 emergency: you pay the $250 deductible; the insurer covers 90% of the remaining $2,750 (about $2,475). You’re out $800 + $250 = $1,050 total, but you dodged a $3,000 bill — insurance «wins» by roughly $1,950.
    • The breakeven point is roughly one mid-size claim (around $900–$1,000) every year, or one larger claim every 2–3 years.

    Since most healthy pets don’t hit a vet emergency every single year, the real question isn’t «will I use it this year» — it’s «would an unexpected $3,000–$10,000 bill wreck my budget if it happened once?»

    When pet insurance is probably worth it

    • You couldn’t comfortably pay a surprise $3,000–$10,000 vet bill in cash.
    • You have a breed prone to expensive conditions (hip dysplasia, bloat, cancer-prone breeds).
    • You enroll your pet young, before any condition becomes «pre-existing» and gets excluded. [enlace: #35]
    • You want cost to never be the reason you decline a treatment your vet recommends.
    • You’re getting a puppy or kitten and want coverage locked in before anything shows up on a vet record.

    When it’s probably not worth it

    • You already have $5,000–$10,000 in accessible savings you’re genuinely willing to earmark for pet emergencies.
    • Your pet is older and premiums have climbed into the $150–$250+/month range, while your calculated «worst case» still stays affordable.
    • You adopted a senior pet with a pre-existing condition insurance won’t cover anyway. [enlace: #35]
    • You know you won’t actually set aside the premium difference each month if you skip coverage.

    Pet insurance vs. a self-funded emergency fund

    Pet insuranceDIY savings account
    Covers a $10,000 emergency in year oneYes, after deductible and waiting periodOnly if you’ve already saved that much
    Money lost if your pet stays healthyYes — premiums aren’t refundedNo — the money is still yours
    Needs discipline to workNo — automaticYes — you must actually not spend it
    Pre-existing conditionsExcluded [enlace: #35]Covered — it’s just your own money
    Best forUnpredictable, large bills early in a pet’s lifeOwners with strong savings discipline and a cash cushion already

    Most people who try pure self-insurance eventually either match premium-level monthly contributions anyway, or get caught short by a big bill before they’ve saved enough.

    What pet owners and vets actually say

    About 67% of insured pet owners said in a Consumer Reports survey that their coverage was worth the cost — but only 34% said they’d saved more in claims than they’d paid in premiums, meaning plenty of satisfied owners still «lost» the bet in pure dollar terms; they were paying for peace of mind, not a profit. Separately, 9 in 10 of 557 veterinary professionals surveyed said insurance reduces their clients’ anxiety about cost, and 30% said they adjust treatment plans five or more times a week because of cost concerns — insurance is partly a hedge against having to say no to your own vet. (Pawlicy)

    How to decide: a 60-second checklist

    1. Add up what you could pay in cash tomorrow for a pet emergency without touching rent or debt payments.
    2. If that number is under $3,000, lean toward insurance — or start a dedicated pet fund today, before you need it.
    3. Check your breed’s known risk conditions and your pet’s age; younger and higher-risk pets tip toward insurance.
    4. Get 2–3 real quotes for your actual pet and compare the premium to what you’d need to save monthly to self-insure. [enlace: #3]
    5. If you go without insurance, open a separate savings account today and fund it like a bill, not a leftover.

    Frequently asked questions

    Does pet insurance actually save most people money?

    No — in most years, for most pets, premiums paid exceed claims received. The product is financial protection against a rare large bill, similar to home or car insurance, not a savings plan.

    Is it worth it for an older pet?

    Often harder to justify. Premiums rise with age while new conditions become excluded as «pre-existing» once diagnosed, so coverage is most valuable when bought young. [enlace: #35]

    Can I just save the premium money instead?

    Yes, if you’re disciplined enough to actually set it aside every month and a large bill doesn’t hit before you’ve built a cushion. Many owners intend to self-insure and never build the fund.

    Does insurance make vets recommend more treatment?

    Surveyed vets report the opposite concern is more common: without insurance, cost often limits what owners agree to, not the reverse.

    The bottom line

    Pet insurance isn’t a guaranteed win in dollar terms — most policyholders pay more in premiums than they get back in claims. What it reliably buys is protection against the one bad year: a $5,000–$10,000 emergency that would otherwise mean a hard financial choice, or worse, having to decline treatment. If you could pay that bill in cash without stress, you can self-insure. If you couldn’t, the math tips toward coverage — ideally bought while your pet is young and healthy.

    This article is for general information and isn’t personalized financial advice. Run the numbers for your own pet, income and risk tolerance before deciding.


    Sources

  • How Does Pet Insurance Work?

    How Does Pet Insurance Work?

    How Does Pet Insurance Work? A Plain-English Guide (2026)

    Last updated: October 2026 · Reading time: 9 minutes

    Your dog swallows a sock on a Sunday night. The emergency vet quotes $3,800 for surgery. That moment is exactly what pet insurance is built for, but only if you understand how it works before you need it.

    This guide explains, in plain English, how pet insurance works in the United States: what you pay, what the insurer pays, and the fine print that decides whether a claim gets approved.

    Quick answer: Pet insurance works on reimbursement. You pay the vet bill, send the invoice to your insurer, and they pay you back a set percentage (usually 70%, 80% or 90%) after you’ve met your deductible, up to your annual limit. It covers new accidents and illnesses after a waiting period. It does not cover pre-existing conditions or, usually, routine care.

    Pet insurance in 30 seconds

    Five numbers define every pet insurance policy. Once you know them, any quote becomes easy to compare:

    TermWhat it meansTypical options
    PremiumWhat you pay each month to keep the policy active~$23/month for cats, ~$43/month for dogs (accident and illness)
    DeductibleWhat you pay yourself before the insurer starts paying$100, $250, $500 or $1,000
    Reimbursement rateThe share of the bill the insurer pays after the deductible70%, 80% or 90%
    Annual limitThe maximum the insurer pays per policy year$2,500 to unlimited
    Waiting periodTime after you sign up before coverage starts1–15 days for accidents, 14–30 days for illness

    Average premiums are 2026 medians from Insurify, based on more than 250,000 quotes. Your price will depend on your pet’s age, breed and ZIP code.

    How pet insurance works, step by step

    1. You choose a plan and pay a monthly premium

    You pick a coverage type, a deductible, a reimbursement rate and an annual limit. The insurer prices the policy based on your pet’s species, breed, age and where you live. You pay the premium monthly or once a year (annual payment often comes with a small discount).

    2. You wait out the waiting period

    Coverage doesn’t start the day you buy. Insurers add a waiting period so people can’t buy a policy after their pet is already sick. Accident coverage often starts within a few days, illness coverage after about two weeks, and orthopedic problems like a torn cruciate ligament can take months. [enlace: #6]

    3. Your pet gets sick or hurt, and you go to any licensed vet

    Unlike human health insurance, most U.S. pet insurance has no network. You can use your regular vet, a specialist or a 24-hour emergency hospital.

    4. You pay the bill and file a claim

    In most cases you pay the vet first. Then you upload the itemized invoice (and sometimes medical records) through the insurer’s app or website. A few insurers can pay the vet directly at checkout, which helps if you can’t cover a large bill up front.

    5. The insurer reviews the claim

    The claims team checks that the condition is covered, isn’t pre-existing and didn’t start during the waiting period. Simple claims can be approved in minutes; complex ones, or the first claim on a new policy, can take a few weeks while they review medical history. [enlace: #10]

    6. You get reimbursed

    The insurer subtracts any deductible you haven’t met yet, applies your reimbursement rate and sends you the money by direct deposit or check, up to your annual limit.

    The four numbers that decide what you get back

    Deductible

    Your deductible is the amount you pay before coverage kicks in. Most U.S. insurers use an annual deductible: you pay it once per policy year, no matter how many conditions your pet has. A few use a per-condition deductible, paid once for each new illness or injury, which can be cheaper over time for a pet with one chronic problem. A higher deductible lowers your premium but raises what you pay when something happens. [enlace: #4]

    Reimbursement rate

    This is the percentage of the covered bill (after the deductible) that the insurer pays. At 90%, a $1,000 covered bill gets you $900 back; at 70%, you get $700. Going from 70% to 90% usually adds a few dollars a month to the premium. [enlace: #5]

    Annual limit

    The annual limit caps what the insurer pays in one policy year. Common choices are $5,000, $10,000 or unlimited. For a young dog with no issues, $5,000 is often enough; for breeds prone to expensive conditions (cancer, hip dysplasia, spinal disease), an unlimited or high limit is safer.

    Waiting period

    Covered earlier, but worth repeating: anything that shows symptoms during the waiting period is usually treated as pre-existing for the life of the policy. That’s why enrolling while your pet is young and healthy matters so much.

    The three types of pet insurance plans

    Plan typeWhat it coversBest forTypical cost (2026)
    Accident and illnessInjuries plus illnesses: infections, cancer, allergies, digestive problems, emergency surgery, hospital stays, diagnosticsMost pet owners~$43/month dogs, ~$23/month cats
    Accident-onlyInjuries only: broken bones, swallowed objects, bite wounds, car accidentsTight budgets or older pets that can’t get full coverage~$16/month dogs, ~$9/month cats
    Wellness add-onRoutine care: vaccines, annual exams, flea and tick prevention, sometimes dental cleaningsOwners who want predictable routine costs spread monthlyExtra $10–$30/month

    Accident-only averages come from NAPHIA data via Insurify. Most policyholders choose accident and illness coverage, because illness, not accidents, drives most big vet bills.

    Wellness add-ons are not insurance in the strict sense: they reimburse fixed amounts for planned care. Run the numbers before adding one; many owners pay about what they’d spend anyway. [enlace: #8]

    What pet insurance usually covers

    An accident and illness plan typically pays for:

    • Emergency visits and hospitalization
    • Surgery, including foreign-object removal and tumor removal
    • Diagnostics: X-rays, ultrasound, MRI, blood work
    • Cancer treatment, including chemotherapy and radiation
    • Chronic conditions diagnosed after enrollment, like diabetes or allergies
    • Hereditary and congenital conditions (with most major insurers)
    • Prescription medications
    • Some insurers also include exam fees, behavioral therapy and alternative treatments like acupuncture; others charge extra or exclude them

    What pet insurance doesn’t cover

    These exclusions cause most denied claims, so read them before you buy:

    • Pre-existing conditions: anything your pet showed signs of before coverage started or during the waiting period. Some insurers will cover a curable condition again after your pet has been symptom-free for 12 months. [enlace: #35]
    • Routine and preventive care, unless you add a wellness plan
    • Cosmetic or elective procedures, such as ear cropping, tail docking and declawing
    • Breeding, pregnancy and birth costs
    • Dental illness, with some insurers (others cover it if your pet has had a recent dental exam)
    • Orthopedic problems during a longer waiting period, especially cruciate ligament tears and hip dysplasia

    The full list is in the policy’s «exclusions» section. It’s usually two or three pages and worth ten minutes of your time. [enlace: #9]

    Waiting periods: what to expect

    CoverageTypical waiting periodExamples
    Accidents1–15 daysNext day with MetLife and Embrace; 2 days with Lemonade
    Illnesses14–30 days14 days with MetLife, Embrace and Lemonade
    Orthopedic / cruciate ligament14 days to 12 monthsVaries widely; some insurers waive it after a vet exam

    Examples from GoodRx (2025). Always confirm in the current policy, as insurers update terms often.

    How much does pet insurance cost?

    Age is the biggest factor. Median accident and illness premiums in 2026, according to Insurify:

    AgeDogCat
    Puppy / kitten$40/month$21/month
    Adult$46/month$22/month
    Senior$116/month$62/month

    Beyond age, your premium depends on:

    • Breed: French Bulldogs, English Bulldogs and Great Danes cost more to insure than mixed breeds.
    • Location: premiums are higher where vet care is more expensive, like large cities.
    • Your choices: a higher deductible, lower reimbursement rate or lower annual limit all reduce the premium.

    Premiums also rise over time. U.S. pet insurance premium volume grew about 21% in 2025 while the number of insured pets grew 9%, which means the average policy is getting more expensive, largely because vet care is (Insurance Business, NAPHIA 2026). [enlace: #3]

    A real-world example: the $3,800 sock

    Let’s go back to the dog who swallowed a sock. Say the owner has an accident and illness policy with a $250 annual deductible, 90% reimbursement and a $10,000 annual limit, and this is the first claim of the year.

    StepAmount
    Emergency surgery bill$3,800
    Minus deductible (paid by owner)−$250
    Covered amount$3,550
    Insurer pays 90%$3,195
    Owner pays (deductible + 10%)$605

    At about $43 a month, that owner paid roughly $516 in premiums for the whole year. One emergency covered the cost of the policy six times over. Without insurance, the full $3,800 would have come out of pocket.

    The flip side: if the dog stays healthy all year, the $516 is gone. Pet insurance is protection against a big, unexpected bill, not a way to save money on routine care.

    Is pet insurance worth it?

    It usually makes sense if:

    • An unexpected bill of $2,000–$5,000 would hurt your finances or force a hard decision
    • Your pet is young and healthy, so nothing is pre-existing yet
    • Your breed is prone to costly conditions, such as hip dysplasia, cancer, spinal or heart disease

    It may not be worth it if you have a dedicated emergency fund of $5,000 or more set aside for your pet, or if your pet is very old and most problems would be excluded as pre-existing.

    Only about 4% of U.S. pets are insured, according to NAPHIA, so most owners are carrying this risk on their own. For a deeper breakdown with real vet bills, see our guide on whether pet insurance is worth it. [enlace: #2]

    How to choose a pet insurance plan in 5 steps

    1. Get quotes while your pet is young. Prices rise with age and every new symptom becomes a future exclusion.
    2. Pick the annual limit first. Choose $10,000 or unlimited for large or high-risk breeds; $5,000 can work for small, healthy mixed breeds.
    3. Balance deductible and reimbursement. A $250–$500 deductible with 80–90% reimbursement is the sweet spot for most owners.
    4. Read the exclusions and waiting periods. Check orthopedic waiting periods, hereditary coverage and whether exam fees are included.
    5. Compare at least three insurers. The same pet can get very different prices from different companies. [enlace: #11]

    Frequently asked questions

    Do I have to use a specific vet?

    No. Most U.S. pet insurance policies let you visit any licensed veterinarian, specialist or emergency hospital.

    Does pet insurance cover pre-existing conditions?

    Not usually. Conditions that showed signs before your coverage started are excluded. Some insurers will cover curable conditions again after your pet has been symptom-free for about 12 months.

    How long does it take to get reimbursed?

    Simple claims can be approved within minutes or a few days. The first claim on a new policy, or a complex one, may take a few weeks while the insurer reviews your pet’s medical records.

    Can I get pet insurance for an older pet?

    Yes, many insurers have no upper age limit for new enrollments, but premiums are much higher for senior pets and more conditions may be excluded as pre-existing.

    Is there a deductible every time I go to the vet?

    With an annual deductible, no: you pay it once per policy year. With a per-condition deductible, you pay it once for each new illness or injury.

    Can I cancel pet insurance anytime?

    Most insurers let you cancel at any time, often with a refund for unused premiums. Check whether your state or insurer has a free-look period, usually 10–30 days after purchase.

    The bottom line

    Pet insurance works by reimbursing you for covered vet bills after you pay a deductible, at the percentage you choose, up to an annual limit. The key is to buy it before problems start, read the exclusions and pick limits that match your pet’s breed and your budget. Once you understand those four numbers, you can compare any two quotes in minutes.

    This article is for general information only and isn’t financial or veterinary advice. Coverage details vary by insurer and state; always read the policy before buying.


    Sources

  • Hello world!

    Welcome to WordPress. This is your first post. Edit or delete it, then start writing!